Homeowners Insurance in Jupiter, FL
Local, independent agents who compare coverage from dozens of carriers for Jupiter and Tequesta homes, from river lots in Pennock Point to newer homes in Abacoa.

- Independent agency since 2017
- 40+ carrier appointments
- Local office in Stuart
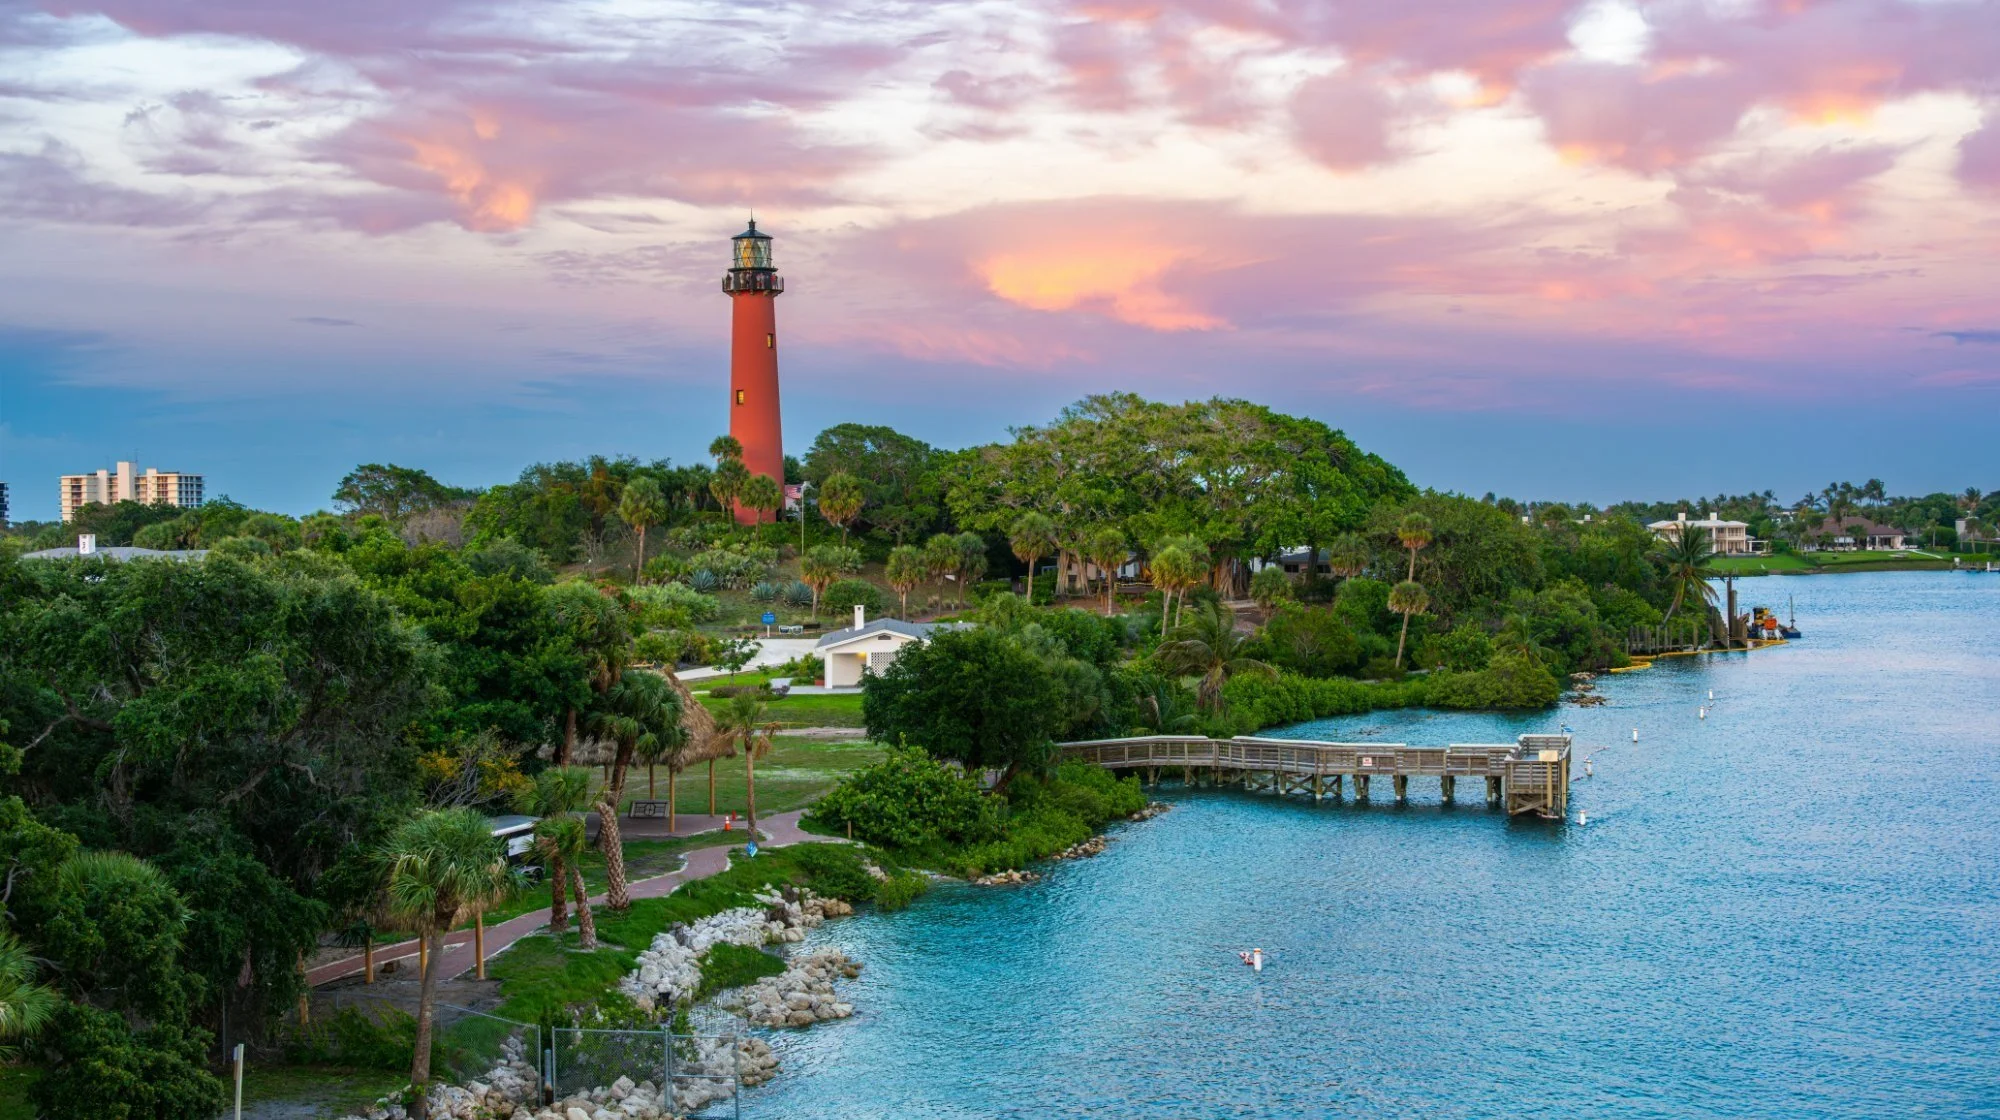
Insuring a home in Jupiter isn't like insuring one in the middle of the state. You've got salt air, the Loxahatchee and the Intracoastal, hurricane season every year, and a mix of homes that runs from 1970s block ranches to brand new construction. That's a lot for one insurance company's rulebook to handle, and it's why so many Jupiter homeowners end up with a policy that doesn't quite fit.
We're an independent agency, so we're not tied to one company. We compare options across our carriers, explain what each one actually covers, and help you pick the policy that makes sense for your home and your budget.
Home insurance built around how Jupiter actually lives
No two Jupiter neighborhoods look the same to an insurance company, and your quote reflects that.
Waterfront homes on the Loxahatchee and the Intracoastal
River and Intracoastal homes are some of the most beautiful in Palm Beach County, and they're also the ones carriers look at most closely. Distance to the water, elevation, docks, lifts and seawalls all come into play. We'll help you understand how different policies handle those features, and we'll price flood coverage right alongside your home policy so nothing falls through the cracks.
Established neighborhoods with older homes
Homes in places like Abacoa, Jonathan's Landing, Admirals Cove, Egret Landing and Mallory Creek often have newer roofs and impact-rated windows and doors. Those features can make a real difference in price, so make sure they're documented. A current wind mitigation report is the easiest way to do that.
Acreage homes in Jupiter Farms
Out west, it's more about space: detached garages, barns, fences, pools and sometimes horses. We'll talk through coverage for other structures and liability so the whole property is accounted for, not just the house.
From our quoting desk
What we're seeing in Jupiter right now
Updated
- On older homes in established neighborhoods like Pennock Point, roof age and a current 4-point inspection come up first. Having a recent inspection report ready when you request a quote cuts down the back and forth.
- Waterfront homes on the Loxahatchee River and the Intracoastal often need more than one market. Some fit a high-value carrier better than a standard homeowners policy, so we look at both paths at the same time.
- In gated and golf communities like Jonathan's Landing, Admirals Cove and Abacoa, the most common question is who covers what between the HOA master policy and your own policy, especially for villas and townhomes. Your HOA documents usually answer it, and we can walk through them with you.
- On acreage in Jupiter Farms, detached garages, barns, fencing and pool cages are easy to overlook. List them when you request a quote so the whole property is accounted for, not just the house.
- Seasonal owners don't always realize that months away from the home can affect coverage. Tell us how long the home sits empty each year so we can match the policy to how you actually use it.
These are general observations from the quotes our team has worked recently, not a prediction of what any carrier will offer on your home.
What a Jupiter homeowners policy usually covers
Most policies are built from the same building blocks. What changes from one company to the next is the fine print, the limits and the deductibles.
| Coverage | What it's for | Jupiter example |
|---|---|---|
| Dwelling | The structure of your home | Roof and wall damage after a windstorm |
| Other structures | Things not attached to the house | Fence, detached garage, pool cage |
| Personal property | Your belongings | Furniture and electronics damaged by a covered loss |
| Loss of use | Extra living costs if you can't stay home | A rental while repairs are made after a covered loss |
| Personal liability | Injuries or damage you're legally responsible for | A guest slips on your pool deck |
| Medical payments | Small medical bills for guests, regardless of fault | A neighbor's child hurt on your property |
What isn't covered
Flood and storm surge aren't covered by a standard homeowners policy. Neither is wear and tear, mold from long-term leaks, or damage from poor maintenance. Some water damage is limited too, depending on the policy. We'll point out the gaps before you buy, not after a claim.
What a wind mitigation inspection scores
Form OIR-B1-1802 (Rev. 04/26)
A lot of Jupiter homes, especially older ones in established neighborhoods and along the river, already have features that can earn wind credits. They just haven't been documented. Here's what the inspector looks at. Florida's My Safe Florida Home program may also offer free inspections and grants to eligible homeowners.
- Building code year. When the house was permitted. It's a fixed feature you can't change, and on many older Jupiter homes it carries real weight on the form.
- Roof covering. The material and whether it meets current wind standards. It's tied to roof age, one of the biggest factors in what you'll pay for home insurance here.
- Roof deck attachment. How the sheathing is fastened to the trusses. Nail size and spacing both matter, and the difference shows up on the form.
- Roof to wall connection. Toe nails, clips, single wraps or double wraps. Stronger connections score noticeably better than toe nails.
- Roof geometry. Hip, gable or other. It's a fixed feature, and hip roofs typically score better than gable roofs.
- Secondary water resistance. A sealed layer under the roof covering. It's most often added when the roof is replaced, so ask your roofer about it before the work starts.
- Opening protection. Impact-rated windows and doors, or shutters, on every opening. Partial protection usually scores as none, so every opening needs to be covered.
New on the 2026 version of the form
The revised OIR-B1-1802, used for inspections on or after April 1, 2026, adds a design wind speed region field, a roof slope field and a spot for FORTIFIED Home certificates. Inspectors also have to back up each rated feature with photos. If your report was done on the older version, ask us whether it will still work for your quote.
Have a wind mitigation report? Mention it when you request a quote so carriers can rate your home's features.
Start My Jupiter QuoteMore on how this differs from a 4-point or roof inspection in our guide to Florida home insurance inspections.
Hurricanes, wind and your deductible
How a hurricane deductible works
Most Florida policies have two deductibles: one for everyday claims and a separate hurricane deductible, usually a percentage of your dwelling coverage. On a home with $600,000 of dwelling coverage, a 2% hurricane deductible is $12,000. A 5% deductible is $30,000. A higher deductible lowers your premium, but you'll want to be comfortable covering that amount after a storm. We'll show you both numbers side by side.
Flood insurance in Jupiter
All of Florida is in a flood zone. The only difference is whether you're in a high risk zone or a low risk one. Jupiter's mix of river, Intracoastal and oceanfront means plenty of homes sit in high risk zones, but flooding from heavy rain happens inland too. Your homeowners policy won't cover it, so it's worth pricing flood coverage even if your lender doesn't require it. Not sure of your zone? Palm Beach County's flood zone lookup will tell you, and we can help you read the results.
| What you're comparing | Standard homeowners policy | NFIP flood policy | Private flood policy |
|---|---|---|---|
| Covers rising water and storm surge | No | Yes | Yes |
| Building coverage limit | Not for flood | Up to $250,000 | Often higher, varies by company |
| Contents coverage | Not for flood | Up to $100,000, purchased separately | Varies by company |
| Extra living expenses | Not for flood | Not included | Sometimes included |
| Waiting period | Not for flood | Usually a waiting period before coverage starts | Varies by company, sometimes shorter |
| Best fit | Wind, fire, theft, liability | Most homes, especially with a mortgage | Higher-value or waterfront homes needing higher limits |
What drives home insurance prices in Jupiter
Here's what carriers look at when they price a Jupiter home. Some of these you can change, and some you can't.
- You can influence this
- Fixed factor
-
Roof age and shape
Newer roofs and hip roofs usually price better.
You can influence this -
Year built and updates
Updated electrical, plumbing and AC help, especially on older homes.
You can influence this -
Construction type
Concrete block and newer building methods tend to rate better than older frame homes.
Fixed factor -
Opening protection
Impact windows, doors and shutters can earn wind credits.
You can influence this -
Distance to the coast
Oceanfront, Intracoastal and river homes carry more wind exposure.
Fixed factor -
Claims history
Recent claims can affect your options and price.
Fixed factor -
Deductibles you choose
A higher hurricane deductible lowers premium, but raises what you'd pay after a storm.
You can influence this
Why Jupiter homeowners work with an independent agency
| Captive agent | Direct online company | Independent agency (us) | |
|---|---|---|---|
| Carriers available | One | One | More than 40 carrier appointments |
| Re-shopping at renewal | Only within that company | You do it yourself | We can re-shop for you |
| Help with older homes or unusual properties | Limited to one set of guidelines | Limited | Many carriers' guidelines |
| Local help after a storm | Varies | Usually a call center | A local Treasure Coast team |
We're a family-owned agency in Stuart, and we've been helping Treasure Coast and northern Palm Beach County homeowners since 2017. Our team handles homeowners insurance together, so you'll get consistent help whoever picks up the phone.
Serving Jupiter, Tequesta and northern Palm Beach County
We work with homeowners across Jupiter's 33458 and 33477 ZIP codes, plus Tequesta, Jupiter Inlet Colony, Juno Beach and Palm Beach Gardens. Our office is a short drive north in Stuart, and most Jupiter clients handle everything by phone, email and e-signature. Just over the county line, we also help homeowners in Hobe Sound, Stuart, Palm City, and Jensen Beach.
Manchester Insurance, 1239 SE Indian St, Suite 101, Stuart. Serving Jupiter and Tequesta.
Coverage that pairs with your Jupiter home policy
- Flood insurance Your home policy doesn't cover flood. Here's what does. Learn more
- High value home insurance For larger Jupiter homes that need broader coverage. Learn more
- Umbrella insurance Extra liability protection for pools, docks and guests. Learn more
- Auto insurance Quote your cars with the same team that handles your home. Learn more
- Condo insurance Own a condo in Jupiter or Tequesta? Start here. Learn more
Let's compare your Jupiter home insurance options
Tell us about your home once. We'll shop the carriers that fit your home, lay the options out side by side, and walk you through the differences so you can choose with confidence. No pressure and no obligation.
Jupiter homeowners insurance FAQs
How much does homeowners insurance cost in Jupiter, FL?
It depends more on the house than the ZIP code. Roof age and shape, year built, construction type, distance to the water, wind mitigation features, claims history and the deductible you pick all move the price. Two homes on the same Jupiter street can come back very differently. The quickest way to get a real number is a quote that compares several carriers side by side.
Why is home insurance so expensive in Jupiter?
Jupiter is a coastal town with a lot of waterfront property, so hurricane and wind risk drive much of the cost. Construction costs, what carriers pay for their own reinsurance, and Florida's claims environment play a part too. Homes with newer roofs, impact windows or shutters, and a current wind mitigation report often price better.
Does homeowners insurance cover hurricane damage in Jupiter?
Most Florida homeowners policies cover wind damage from a hurricane, subject to a separate hurricane deductible. Flooding and storm surge are not covered by a standard homeowners policy. That takes a separate flood policy, which we can quote alongside your home insurance.
What is a hurricane deductible?
A hurricane deductible applies to hurricane wind losses instead of your regular deductible. It is usually a percentage of your dwelling coverage, like 2% or 5%, rather than a flat dollar amount. On a home with $600,000 of dwelling coverage, a 2% hurricane deductible means the first $12,000 of a covered hurricane loss is yours. We can show you how different deductible options change your premium.
Do I need flood insurance in Jupiter if I'm not in a high risk flood zone?
All of Florida is in a flood zone. The only difference is whether your home sits in a high risk zone or a low risk one. Standard homeowners policies don't cover flood, and plenty of flood claims come from homes outside high risk zones. Even if your lender doesn't require it, flood coverage is worth pricing, and it is often more affordable in lower risk zones.
What is a wind mitigation inspection and can it lower my premium?
A wind mitigation inspection documents features that help your home stand up to wind, like roof shape, how the roof is attached to the walls, roof deck attachment and protection on windows and doors. Carriers use the report when they rate your policy, and qualifying features can lower the wind portion of your premium. If you already have a report, mention it when you request a quote.
My Jupiter home is older. Can I still get coverage?
Often, yes. Many carriers ask for a 4-point inspection on older homes, which looks at the roof, electrical, plumbing and HVAC. Roof age and condition matter a lot. Because we work with many carriers, a home that doesn't fit one company's guidelines may fit another's.
Do you insure waterfront homes with docks, boat lifts or seawalls?
Yes. We insure waterfront homes along the Loxahatchee River, the Intracoastal and Jupiter's canals. Docks, lifts and seawalls are handled differently from one policy to the next, so it's worth asking how each option treats them. Your boat usually needs its own policy, and we can quote that too.
Do you have an office in Jupiter?
Our office is in Stuart, a short drive north of Jupiter on US-1. Most Jupiter clients handle everything by phone, email and e-signature, and you're always welcome to stop by the office.
Why work with an independent agency instead of buying direct?
A captive agent or a direct company can only offer its own policies. As an independent agency appointed with more than 40 carriers, we can compare options side by side, explain the differences in plain English, and re-shop your policy at renewal if the price or coverage changes.
Do you insure homes in Tequesta, Juno Beach and Palm Beach Gardens?
Yes. We work with homeowners throughout northern Palm Beach County, including Tequesta, Jupiter Inlet Colony, Juno Beach and Palm Beach Gardens, plus Treasure Coast communities like Hobe Sound, Stuart, Palm City, Jensen Beach and Port St. Lucie.
What do I need to get a homeowners insurance quote?
Your address, the year the home was built, roof type and the year it was replaced, square footage, and any updates to electrical, plumbing or HVAC. If you have them, your current declarations page and any wind mitigation or 4-point reports help us get accurate quotes faster.
Six terms worth knowing before you compare quotes
Coverage A
Your dwelling limit, the most the policy will pay to repair or rebuild the house. It should reflect what it would cost to rebuild, not what the house would sell for or what you paid. Your hurricane deductible is usually a percentage of this number, which is why it matters more than people think.
All other perils deductible
The deductible that applies to most covered losses other than a hurricane. It's usually a flat amount like $1,000 or $2,500, and it's separate from your hurricane deductible.
Loss assessment
Coverage for your share when a homeowners or condo association bills owners for damage the master policy didn't fully cover. The default limit is often small. If you own a villa or townhome in a Jupiter community like Jonathan's Landing, Admirals Cove or Abacoa, it's worth checking this limit before you compare prices.
Ordinance or Law
Helps pay, up to its limit, the extra cost of rebuilding to current code instead of how the house was originally built. On an older Jupiter home, the gap between how it was built and what today's code requires can be substantial.
Screen enclosure coverage
Some policies limit or exclude wind damage to screened pool cages unless you add coverage back. If your enclosure would be expensive to replace, ask how each quote handles it before you compare prices.
Elevation certificate
A surveyed document showing how high your lowest floor sits compared with the base flood elevation. It drives flood pricing in AE and VE zones. If your home is in the Town of Jupiter, the Building Department can tell you whether a certificate is already on file. Start with the Town of Jupiter's flood zone page.